Trial Lawyer’s Journal is built on the voices of trial lawyers like you. Share your journey, insights, and experiences through articles, interviews, and our podcast, Celebrating Justice.
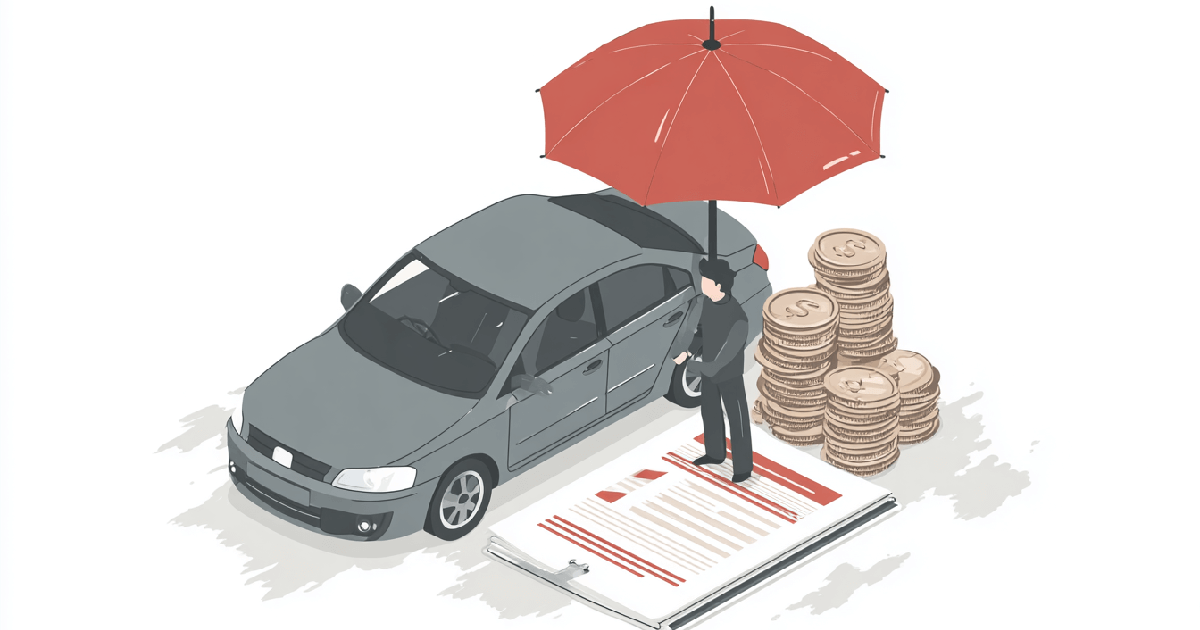
Liability insurance is a type of insurance coverage that protects individuals and organizations from financial loss if they are found legally responsible for causing injury or damage to another person or their property. This protection extends to legal fees and any settlements or judgments that may arise from such incidents.
Property damage liability: Pays for repairs or replacement of another person’s property that you have damaged.
Personal injury liability: Protects against claims of defamation, slander or false advertising.
Professional liability: Also known as errors and omissions insurance, it safeguards professionals against claims of negligence or inadequate work. investopedia.com
How does liability insurance work?
When an incident occurs that results in injury or damage, the affected party may file a claim against you. Your liability insurance policy would then cover the legal costs and any settlements up to your policy’s limits. It’s important to note that liability insurance typically does not cover intentional acts or criminal activities.
Having liability insurance is crucial for several reasons:
Financial protection: It shields your personal or business assets from potential lawsuits and claims.
Legal requirement: In many jurisdictions, certain types of liability insurance, such as auto liability, are mandatory.
Peace of mind: Knowing you’re covered allows you to operate without constant fear of potential legal actions.
Types of liability insurance
There are various types of liability insurance designed to cover different scenarios:
General liability insurance: Protects businesses against claims of bodily injury, property damage, and personal injury occurring on their premises or as a result of their operations. nationwide.com
Product liability insurance: Covers manufacturers, distributors and retailers against claims related to the safety of the products they sell.
Professional liability insurance: Also known as malpractice insurance, it protects professionals like doctors, lawyers, and accountants against claims of negligence or inadequate service.
Employer’s liability insurance: Offers protection against claims from employees who suffer job-related injuries or illnesses not covered by workers’ compensation.
Conclusion
Liability insurance serves as a vital safety net, offering financial protection against unforeseen events that could otherwise lead to significant financial hardship. Understanding the different types of liability coverage and assessing your specific needs can help you select appropriate protection, ensuring peace of mind in both personal and professional contexts.
What is liability insurance?
Liability insurance is a type of coverage that protects individuals and businesses from financial loss if they are found legally responsible for causing injury or property damage to others. It covers legal fees, settlements, and judgments arising from accidents or negligence but does not cover intentional acts or criminal activities.
What happens if you don’t have liability insurance?
Without liability insurance, you may be personally responsible for paying damages if someone sues you for injury or property loss. This could result in:
Out-of-pocket expenses for medical bills or repairs.
Legal fees and court costs, which can be expensive even if you win the case.
Potential loss of assets, including savings, property or business earnings. In many cases, liability insurance is legally required, such as for drivers and business owners.
How much liability insurance coverage do you need?
The amount of liability coverage depends on your financial situation, risks and legal requirements. Some key considerations include:
State-mandated minimums for auto or business liability insurance.
Industry-specific risks for professionals (e.g., doctors, lawyers).
Personal assets—higher coverage protects against lawsuits that exceed policy limits. Experts often recommend higher-than-minimum coverage to ensure adequate financial protection.
Does liability insurance cover lawsuits?
Yes, liability insurance covers legal defense costs, settlements and judgments if you are sued for an incident covered under your policy. However, it typically does not cover:
Intentional wrongdoing or criminal acts.
Breach of contract disputes.
Employee injuries, which require separate workers’ compensation coverage. For high-risk professionals, professional liability insurance (e.g., malpractice insurance) is recommended to cover negligence claims.